Showing posts with label time share. Show all posts

Forms auto-populate, but can agents explain them?


As industry moves to paperless, agents must understand contract provisions

BY BERNICE ROSS, MONDAY, SEPTEMBER 17, 2012.
Inman News®
<a href="http://www.shutterstock.com/pic.mhtml?id=79270183">Robot wielding pen</a> image via Shutterstock.Robot wielding pen image via Shutterstock.
As the industry moves to becoming paperless, the new technologies are exacerbating a problem that has existed for years: agents failing to make sure their clients understand the contracts they are signing. Are you taking the necessary steps to protect your clients?
Your clients have found the perfect house but there are already two offers on it. They're in a hurry to submit an offer, so you take out your iPad, pop open the zipForms version of your purchase contract, and auto-fill the contract. The buyers digitally sign the contract, you obtain their deposit check, and you email the offer to the listing agent. The entire process took a little over five minutes -- isn't technology grand?
I have been interviewing managers and broker-owners regarding the major challenges they're facing with new agents. Every broker and manager I have spoken with has cited the same problem: A substantial proportion of all agents have failed to master the fundamentals of the business.

Whether it works or not, QE3 was needed


Commentary: US not in recession, but fiscal cliff, Europe still loom

BY LOU BARNES, FRIDAY, SEPTEMBER 14, 2012 Inman News®
<a href="http://www.shutterstock.com/gallery-4826p1.html?cr=00&pl=edit-00">Albert H. Teich</a> / <a href="http://www.shutterstock.com/?cr=00&pl=edit-00">Shutterstock.com</a>Albert H. Teich / Shutterstock.com
One thing is for sure. Mr. Bernanke's announcement yesterday is the most extraordinary to come out of the Fed since the all-time previous: Paul Volcker on Columbus Day weekend 1979 said the Fed would allow interest rates to rise as high as necessary to defeat inflation.
As today's problems are the polar opposite of 1979, and raising rates had long been the accepted and effective remedy for inflation, and Mr. Volcker's policies succeeded in solving the problem, it is difficult further to compare these two moments.
From yesterday's announcement by the Federal Open Market Committee: "If the outlook for the labor market does not improve substantially, the Committee will continue its purchases of agency mortgage-backed securities, undertake additional asset purchases… until such improvement is achieved in a context of price stability."
The committee "expects that a highly accommodative stance of monetary policy will remain appropriate for a considerable time after the economy strengthens."

Buyers need your help to close on short sales, REOs


Realtor Notebook

BY TERESA BOARDMAN, THURSDAY, AUGUST 2, 2012.
Inman News®
<a href="http://www.shutterstock.com/pic.mhtml?id=84281719">Red tape</a> image via Shutterstock.Red tape image via Shutterstock.
There might be more information than ever before available to consumers on the Internet, but it won't replace real estate agents anytime soon.
More has been added to our role. Sometimes it feels like we are becoming a source for free labor for banks and government agencies who will not allow buyers or sellers to represent themselves. Sometimes, they make information about special programs available only to real estate agents.
Between Neighborhood Stabilization Program homes, traditional foreclosures and Fannie Mae foreclosures called "HomePath" homes, the homebuying process has changed. When a government agency is the seller, they sometimes use a committee to determine if the buyer is qualified to buy the home.  There are processes and there is paperwork, and sometimes representing one buyer or short-sale seller can feel like a full-time job.
The paperwork can be complicated and the instructions are not always clear. There are agents who are avoiding showing certain homes to their buyers because they don't understand the programs and can't handle the paperwork.

10 expenses you can deduct when renting out a room


Real Estate Tax Talk

BY STEPHEN FISHMAN, FRIDAY, AUGUST 3, 2012.
Inman News®
<a href="http://www.shutterstock.com/pic.mhtml?id=95271559">Tax forms</a> image via Shutterstock.Tax forms image via Shutterstock.

Lots of people are trying to earn a few extra bucks by renting out a room in their home. This can not only be a good source of income, but result in tax deductions.

If you rent out a room in your home, the tax rules apply to you in the same way as they do for landlords who rent out entire properties. This means you get to deduct the expenses arising from your rental activity.

There is one big difference, however: You must divide certain expenses between the part of the property you rent out and the part you live in, just as though you actually had two separate pieces of property.
You can fully deduct (or, where applicable, depreciate) any expenses just for the room you rent; for example, repairing a window in the room, installing carpet or drapes, painting the room, or providing your tenant with furniture (such as a bed).

5 ways seasonal marketing is good for business


Sell real estate clients on listings, lifestyle

BY BERNICE ROSS, THURSDAY, AUGUST 23, 2012 Inman News®
<a href="http://www.shutterstock.com/pic.mhtml?id=86273293" target=blank>Oak tree in autumn</a> image via Shutterstock.
Oak tree in autumn image via Shutterstock.

It's hot and muggy, lots of folks are on vacation, and it's tempting to head to the beach or the pool instead of work. But fall is only four weeks away, and with it, fall selling season begins in earnest. This is your last chance to meet the production goals you set for yourself at the beginning of the year.

If you want to kick up your production now and throughout the fall, here are five ways to capitalize on this great time of year.

Using third-party AVMs to price your listings Tips for arriving at a realistic value


BY BERNICE ROSS, MONDAY, AUGUST 13, 2012 Inman News®
<a href="http://www.shutterstock.com/pic.mhtml?id=92243593" target=blank>Magnifying glass on housing</a> image via Shutterstock.Magnifying glass on housing image via Shutterstock.
Let's face it, home sellers are often skeptical about prices, market conditions or the necessity to stage a property to get it sold. While they may not be willing to believe you, many younger clients are willing to believe the information they see online.
Recently I was speaking to a young woman whose family was facing foreclosure for failure to pay their condominium association fees. They had two severely disabled kids. Even though they had medical insurance, the bills had overwhelmed them. They were under the mistaken impression that if they continued to keep up their mortgage payments they could keep their home. Sadly, the homeowners association was enforcing its right to foreclose. The question is whether they could stay in their home possibly through a loan modification?
The family's existing loan was at Chase with the initial loan amount being $290,000. The family had paid the loan down to $275,000. The question was whether Chase would agree to take a principal reduction under the Home Affordable Refinance Program (HARP).

Home equity protection insurance yanked off the market | No explanation from backers, including venture capital firm Kleiner Perkins


BY KEN HARNEY, TUESDAY, JULY 17, 2012 Inman News®

<a href="http://www.shutterstock.com/pic.mhtml?id=73114849">Empty seats</a> image via Shutterstock.Empty seats image via Shutterstock.

Its Silicon Valley venture capital backers saw it as a game-changer for real estate, and envisioned themselves picking off $250 million a year out of a potential $25 billion market: insurance policies that would protect the nation's homeowners from one of their deepest fears -- further losses in their equity.

Known as "Home Value Protection," the plan was featured on CNBC, FOX Business and publicized in news articles across the country.

As recently as June 20, Scott Ryles, chairman and CEO of the company that developed it, San Francisco-based Home Value Insurance Co., told journalists at the National Association of Real Estate Editors' annual conference in Denver that despite continuing home value declines in many local markets, his policyholders "have financial protection and peace of mind knowing they are insured against a housing market that continues to prove difficult to predict."

Internet scams use Re/Max brand Franchisor warns consumers of email account phishing, rental schemes


BY PAUL HAGEY, FRIDAY, JULY 13, 2012 Inman News®
<a href="http://www.shutterstock.com/pic.mhtml?id=83294065">Cybercrime</a> image via Shutterstock.Cybercrime image via Shutterstock.
The Re/Max real estate brand name has been used in at least two recent online scams, one an email account phishing ploy, the other a false rental scheme.

The online scams appear to be part of the larger milieu of Internet fraud, which, according to the FBI, increased 3.4 percent last year in the U.S. and totaled $485.3 million in losses.

The global real estate franchisor, which has more than 90,000 affiliated agents, has issued warnings for both on its website.

A still-active website that "spoofs," or pretends to be a Re/Max website, attempts to obtain victims' email login and password info. The site has no connection to Re/Max, as evidenced by its address: dijitalkataloog.com.

Sales of second homes soar to highest level since 2005


Investment-home sales, nearly half in cash, jump 64.5%

BY INMAN NEWS, FRIDAY, MARCH 30, 2012.
Image via <a href="http://www.shutterstock.com/gallery-86593p1.html">Mikulich Alexander Andreevich</a>/<a href="http://www.shutterstock.com">Shutterstock</a>
Sales of second homes, which include vacation and investment homes, soared in 2011 to their highest market share since the height of the housing boom, according to an annual report from the National Association of Realtors.
NAR’s 2012 Investment and Vacation Home Buyers Survey includes 2,241 responses from U.S. households who bought either new or existing homes in 2011. The association conducted the survey in March 2012 and controlled for age and income.
Investors lead the surge in second-home sales. Sales of investment homes climbed 64.5 percent in 2011, to 1.23 million, from 749,000 the year before, the report said. At the same time, sales of vacation homes increased 7 percent to 502,000, compared to 469,000 in 2010.
Combined, second-home sales accounted for 38 percent of all home sales last year (27 percent investment homes, 11 percent vacation homes), up from 27 percent in 2010 (17 percent investment homes, 10 percent vacation homes). That's the highest share since 2005, when second-home sales made up 40 percent of sales overall.
Meanwhile, owner-occupied home sales fell 15.5 percent year over year in 2011, to 2.78 million, the report said.
"During the past year investors have been swooping into the market to take advantage of bargain home prices," said Lawrence Yun, NAR's chief economist, in a statement.
"Rising rental income easily beat cash sitting in banks as an added inducement. In addition, 41 percent of investment buyers purchased more than one property."
Second-home buyers weren't hesitant to use cash, Yun added. About four out of 10 vacation-home buyers paid in cash last year, while roughly half of investment buyers did. Of those who did finance their purchase, the median down payment was 27 percent, the report said.
Investors paid somewhat more for their purchases in 2011 than in 2010, though vacation-home buyers paid less. The median price for an investment home last year rose 6.4 percent to $100,000 last year, while the median price for a vacation home fell 19.1 percent to $121,300. Distressed properties accounted for half of investment-home sales, 39 percent of vacation-home sales, and 29 percent of primary-home sales.
Primary-home buyers paid a median $167,700 for their purchase in 2011, down 5.1 percent from the year before.
Investors and vacation-home buyers tended to be older and more affluent than primary-home buyers. While the latter had a median age of 39 and earned a median household income of $72,400, the typical investment-home buyer was 50 years old and earned a median household income of $86,100 and the typical vacation-home buyer was also 50 years old with a median income of $88,600.
Investors planned to hold the property for a median five years and generally bought a home that was a median 25 miles from their primary residence. In an indication of flipping activity, 5 percent of homes purchased by investment buyers in 2011 have been resold, up from 2 percent in 2010, the report said. Investors typically bought in suburban areas.
Vacation-home buyers planned to hold the property for a median 10 years and purchased a property that was a median 305 miles away. Vacation-home buyers typically bought in rural or suburban areas.
As in the 2010 survey, the South accounted for the biggest share of second home purchases in 2011, followed by the West.
Region of Home PurchasePrimary
Residences
Vacation
Properties
Investment
Properties
Northeast20%15%15%
Midwest23%12%17%
South35%42%44%
West22%30%23%
Outside the U.S.0%1%0%
Source: NAR
Also as in the 2010 survey, second-home buyers, especially investors, were slightly more ethnically diverse than primary-home buyers. Among primary-home buyers, 82 percent were white, 8 percent were Asian, 7 percent were black, 5 percent were Hispanic, and 1 percent were "other."
Among buyers of investment properties, 76 percent were white, 13 percent were Asian, 8 percent were black, 6 percent were Hispanic, and 1 percent were "other."
Roughly half of second-home buyers purchased through a real estate agent or broker. Second-home buyers were somewhat more likely than primary-home buyers to buy through a foreclosure or trustee sale or directly from an owner the buyer knew.
Purchase MethodPrimary
Residences
Vacation
Properties
Investment
Properties
Through a real estate agent or broker69%55%48%
Foreclosure or trustee sale5%14%17%
Directly from owner whom the buyer knew9%16%17%
Directly from owner whom the buyer didn’t know5%8%7%
Directly from builder or builder’s agent9%3%5%
Other3%5%6%
Source: NAR
Although the report released today is based on responses from U.S. addresses, according to a separate, monthly survey (the Realtors Confidence Index), international purchases accounted for about 3 percent of transactions in 2011, "which would be in addition to today’s findings," NAR spokesman Walter Molony told Inman News.

New Real Estate Poll: Americans Increasingly Optimistic about Homeownership

Americans are significantly more optimistic about homeownership than they were a year ago. That’s according to a new national survey released this week from Prudential Real Estate, a Brookfield Residential Property Services company. According to the second-annual Prudential Real Estate Outlook Survey, a full 60 percent of Americans have favorable views toward the real estate market. That’s up 8 points since last year.

The survey shows that signs of increasing optimism are widespread:
• With interest rates at historically low levels, 96 percent agree or somewhat agree that now is a good time to buy.
• A full 70 percent of respondents have some degree of confidence that property values will improve over the next two years; with an 8 point increase in those very confident or confident compared to last year.
• 63 percent believe that real estate is a good investment despite the recent market volatility; that’s up 11 points from last year.
The survey confirms that despite the recession, homeownership remains a central part of the American Dream. Eight in 10 respondents said homeownership is very important to them; only 15 percent said the economic downturn made homeownership less important.
“Respondents told us what our sales professionals see every day that, despite recent market volatility, homeownership remains integral to the dreams of most Americans and that consumers’ confidence in the housing market is returning,” said Earl Lee, president, Prudential Real Estate. “This is good news for home buyers and sellers, communities and our economy as a whole. As more people look to take advantage of historic interest rates and prices, we believe the foundation for a sustainable recovery is in sight.”
The survey also highlighted strong ties between homeownership and the community: 77 percent agree that homeownership strengthens a sense of community with 87 percent agreeing or somewhat agreeing that neighborhood comprised of homeowners have a stronger sense of community than neighborhoods made up mainly of renters. This is critical in an environment where two in three respondents believe community feelings in America are declining.
Among the generations, 94 percent of respondents believe that finding the right home and community are crucial to helping their family be happy. Only a small minority of older Americans said the recent housing crisis made homeownership less important to them. Nearly half of Gen Y respondents said it made homeownership more important. Gen Y’ers are particularly optimistic about the road ahead with 72% expressing favorable views about the residential real estate market.
“Characteristically, many of these consumers, particularly Gen Y, share a firm sense of family and community,” Lee said. “It’s not surprising now that they’re embracing homeownership to build on that sense.”
The survey also highlighted consumer caution in a recovering real estate market: 93 percent of respondents said that the housing crisis reminds them that they must be more careful about buying and selling property. More than 90 percent of respondents said a good real estate sales professional can help them make the right choices about homes and communities; and 71 percent believe good agent representation is more important than ever, up 4% from last year’s survey.
Methodology: Interviews with 1,251 Americans who are “in the market” to buy or sell a home were conducted online by Palisades Media Ventures and Penn Schoen Berland, between Feb. 10 and 20, 2012. Respondents are aged 25-64 with a household income of at least $50,000, and either recently bought/sold a home or are considering buying/selling a home. The margin of error is +/- 2.8% for all respondents and higher for subgroups.

Consumer Complaints: Loan Modification Scams Highlighted


Recently, the Lawyers’ Committee for Civil Rights Under Law and NeighborWorks® America highlighted the ongoing foreclosure rescue scam crisis during a press conference to identify top consumer complaints in New York.

During this National Consumer Protection Week event, representatives offered guidance on avoiding financial scams, including loan modification scams.

The Federal Trade Commission’s Northeast Regional Office organized the press event, which highlighted the most egregious frauds plaguing New York residents and featured scam avoidance tips from the Better Business Bureau Serving Metropolitan New York, United States Postal Inspection Service, New York Attorney General’s Office, New York State Department of Financial Services, New York City Department of Consumer Affairs and AARP.

The Loan Modification Scam Alert Campaign educates homeowners about the warning signs that indicate that the person or company offering assistance may be a scam. The top three warning signs of a scam are any person or company that:

• Asks for fees in advance of fully providing services
• Guarantees that they’ll stop a foreclosure or get your loan modified.
• Tells you to stop paying your mortgage company and to pay them instead

“Scams present a real threat to homeowners who are afraid of losing their homes, especially now that new bank settlements and government programs are in the headlines. At times like this, we often see a spike in activity among companies who pretend to be authorized by the government, but are, in fact, scams,” says Deborah Boatright, northeast regional director, NeighborWorks America. “Homeowners are advised to seek help from HUD-approved housing counseling agencies, which offer professional assistance free of charge, and to report scam to the authorities. You can do both from www.loanscamalert.org.”

“Homeowners are looking around desperately for solutions and are vulnerable right now. The foreclosure crisis is ongoing, and foreclosure rescue scammers are taking advantage, often pretending to be affiliated with the government or another trusted resource in order to trick distressed homeowners into paying them money for nothing,” said Yolanda McGill, senior counsel for the Lawyers’ Committee’s Loan Modification Scam Prevention Network (LMSPN). “The best way to avoid losing money to a scam is to never pay for foreclosure help. The best help out there is free from HUD-approved housing counseling agencies.”

Since the launch of the Loan Modification Scam Prevention Network complaint database in February 2010, more than 21,000 consumers have reported foreclosure rescue scams totaling over $60 million in lost money, more than doubling last year’s figures of 10,000 complaint reports and $27 million in lost money. Of this year’s total figures, over 1,100 complaints came from New York State consumers, with reported losses of over $4 million, also more than doubling last year’s total figures of 500 complaint reports totaling $2 million in lost money.

The Loan Modification Scam Prevention Network is comprised of the Federal Trade Commission, the Lawyers’ Committee, NeighborWorks America and dozens of national and local agencies and organizations from around the country, including Fannie Mae, Freddie Mac, the Homeownership Preservation Foundation, the U.S. Treasury Department and the U.S. Department of Housing and Urban Development.

KEY REALTY, INC., Serving your Real Estate Needs, Sell Houses or Buy a Home in Rockford,IL and in the surrounding suburbs.  

Follow us at        https://twitter.com/KeyRealtyInc 
Like us at           http://www.facebook.com/KeyRealtyInc
Official Website  http://keyrealtyus.com/ 

What You Need to Know about Cancellation of Mortgage Debt


A lender will, on occasion, forgive some portion of a borrower’s debt. The general tax rule that applies to any debt forgiveness is that the amount forgiven is treated as taxable income to the borrower. Some exceptions to this rule are available, but, until recently, the borrower was required to pay tax on the debt forgiven. A new law enacted in December 2007 provides relief to troubled borrowers when some portion of mortgage debt is forgiven. However, this relief expires on December 31, 2012 and NAR will be working to obtain an extension throughout the year.

Below is some general information you need to know about this law and cancellation of mortgage debt.

General Rule for Debt Forgiveness
If a lender forgives some or all of an individual’s debts, the general rule is that the forgiven amount is treated as ordinary income and the borrower must pay tax on the forgiven amount. Exceptions apply for bankruptcy, insolvency and certain other situations, including mortgage debt.

Current Law for Mortgage Debt
(Jan. 1, 2007 through Dec. 31, 2012): A borrower can be excused from paying tax on forgiven mortgage debt. The debt must be secured by a principal residence and the total amount of the outstanding obligation may not exceed the original mortgage amount plus the cost of any improvements.

Does the relief apply only to a sale?
No. The provision has broader application. Lenders might forgive some portion of mortgage debt in a short sale (when value at sale is less than the amount owed) or in a foreclosure where the debt is wiped out. In addition, if a borrower still living in the home is able to make an arrangement with a lender that reduces the principal balance of a mortgage, the amount forgiven in that workout will not be taxed.

Can the homeowners in a short sale or foreclosure claim a loss?
No. The loss is considered a personal loss and is, therefore, ineligible for either capital loss or ordinary loss treatment.

What happens to the seller when mortgage debt is forgiven?
Until January 1, 2013, the homeowner will pay no tax on any forgiven amount.

Does this provision apply to a refinanced mortgage?
Only in limited circumstances. The relief provision can apply to either an original or a refinanced mortgage. If the mortgage has been refinanced at any time, the relief is available only up to the amount of the original debt (plus the cost of any improvements). Tax relief is generally not available for second mortgages or home-equity lines of credit where the funds are not used for home improvement. Any amount that is not eligible for the relief provision will be taxed as ordinary income.

How does the homeowner get the correct information to the IRS?
The lender is required to provide the homeowner and the IRS with a Form 1099 reflecting the amount of the forgiven debt. The borrower/homeowner must file a Form 982 to reflect the amount forgiven and to show the reason why the forgiven amount is not taxable. Any taxable portion of forgiven debt will then be reported on the homeowner’s Form 1040 for the tax year in which the debt was forgiven.

What if a property declines in value but the owner stays in the house?
The provision would not apply. The provision applies only at the time of sale or other disposition or when there is a workout (reduction of existing debt) with the lender.

Do all lenders forgive mortgage debt when property values decline or the home is in foreclosure?
No. Some states have laws that allow a lender to require a repayment arrangement, particularly if the borrower has other assets. Forgiveness of debt is always at the lender’s discretion.

KEY REALTY, INC., Serving your Real Estate Needs, Sell Houses or Buy a Home in Rockford,IL and in the surrounding suburbs.  

Follow us at        https://twitter.com/KeyRealtyInc 
Like us at           http://www.facebook.com/KeyRealtyInc
Official Website  http://keyrealtyus.com/ 

Own the Smallest Town in America: Buford, Wyo. for Auction


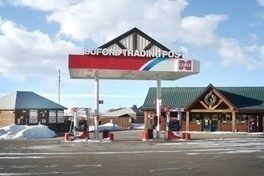
Williams & Williams, a leading brand in real estate auctions, will auction the entire town of Buford, Wyoming on Thursday, April 5 at noon MST. This unique event will offer potential buyers a rare opportunity to own an entire town. Buford is known as the “The Nation’s Smallest Town” with a population of one. It’s also the town with the highest elevation on Interstate 80 at 8,000 feet above sea level.

Despite its size, this historic town has no shortage of visitors and is a must-see destination for many travelers. Included in this income-producing town are five buildings: the Buford Trading Post which sells fuel, snacks and memorabilia, a three-bedroom modular home, a 1905 school house (used as an office), a garage and a 1900s cabin (used as a tool shed). Nearby attractions include Curt Gowdy State Park, Vedauwoo State Park and rock climbing area, the 140-year-old “Tree in the Rock” and the Ames Monument.

“We are offering a rare opportunity to own a town and piece of American history,” says Pam McKissick, Williams & Williams’ CEO. “Owning your own zip code does come with perks—you can be the mayor, sheriff, town council, sole voter or any other position you’d like to create.”

Located midway between Cheyenne and Laramie, Buford is the second oldest town in Wyoming, dating back to the construction of the Transcontinental Railroad. Named after Major General John Buford, a hero of the battle of Gettysburg, the town has been visited by Presidents Ulysses S. Grant and Franklin D. Roosevelt and outlaw Butch Cassidy. 


KEY REALTY, INC., Serving your Real Estate Needs, Sell Houses or Buy a Home in Rockford,IL and in the surrounding suburbs.  

Follow us at        https://twitter.com/KeyRealtyInc 
Like us at           http://www.facebook.com/KeyRealtyInc
Official Website  http://keyrealtyus.com/